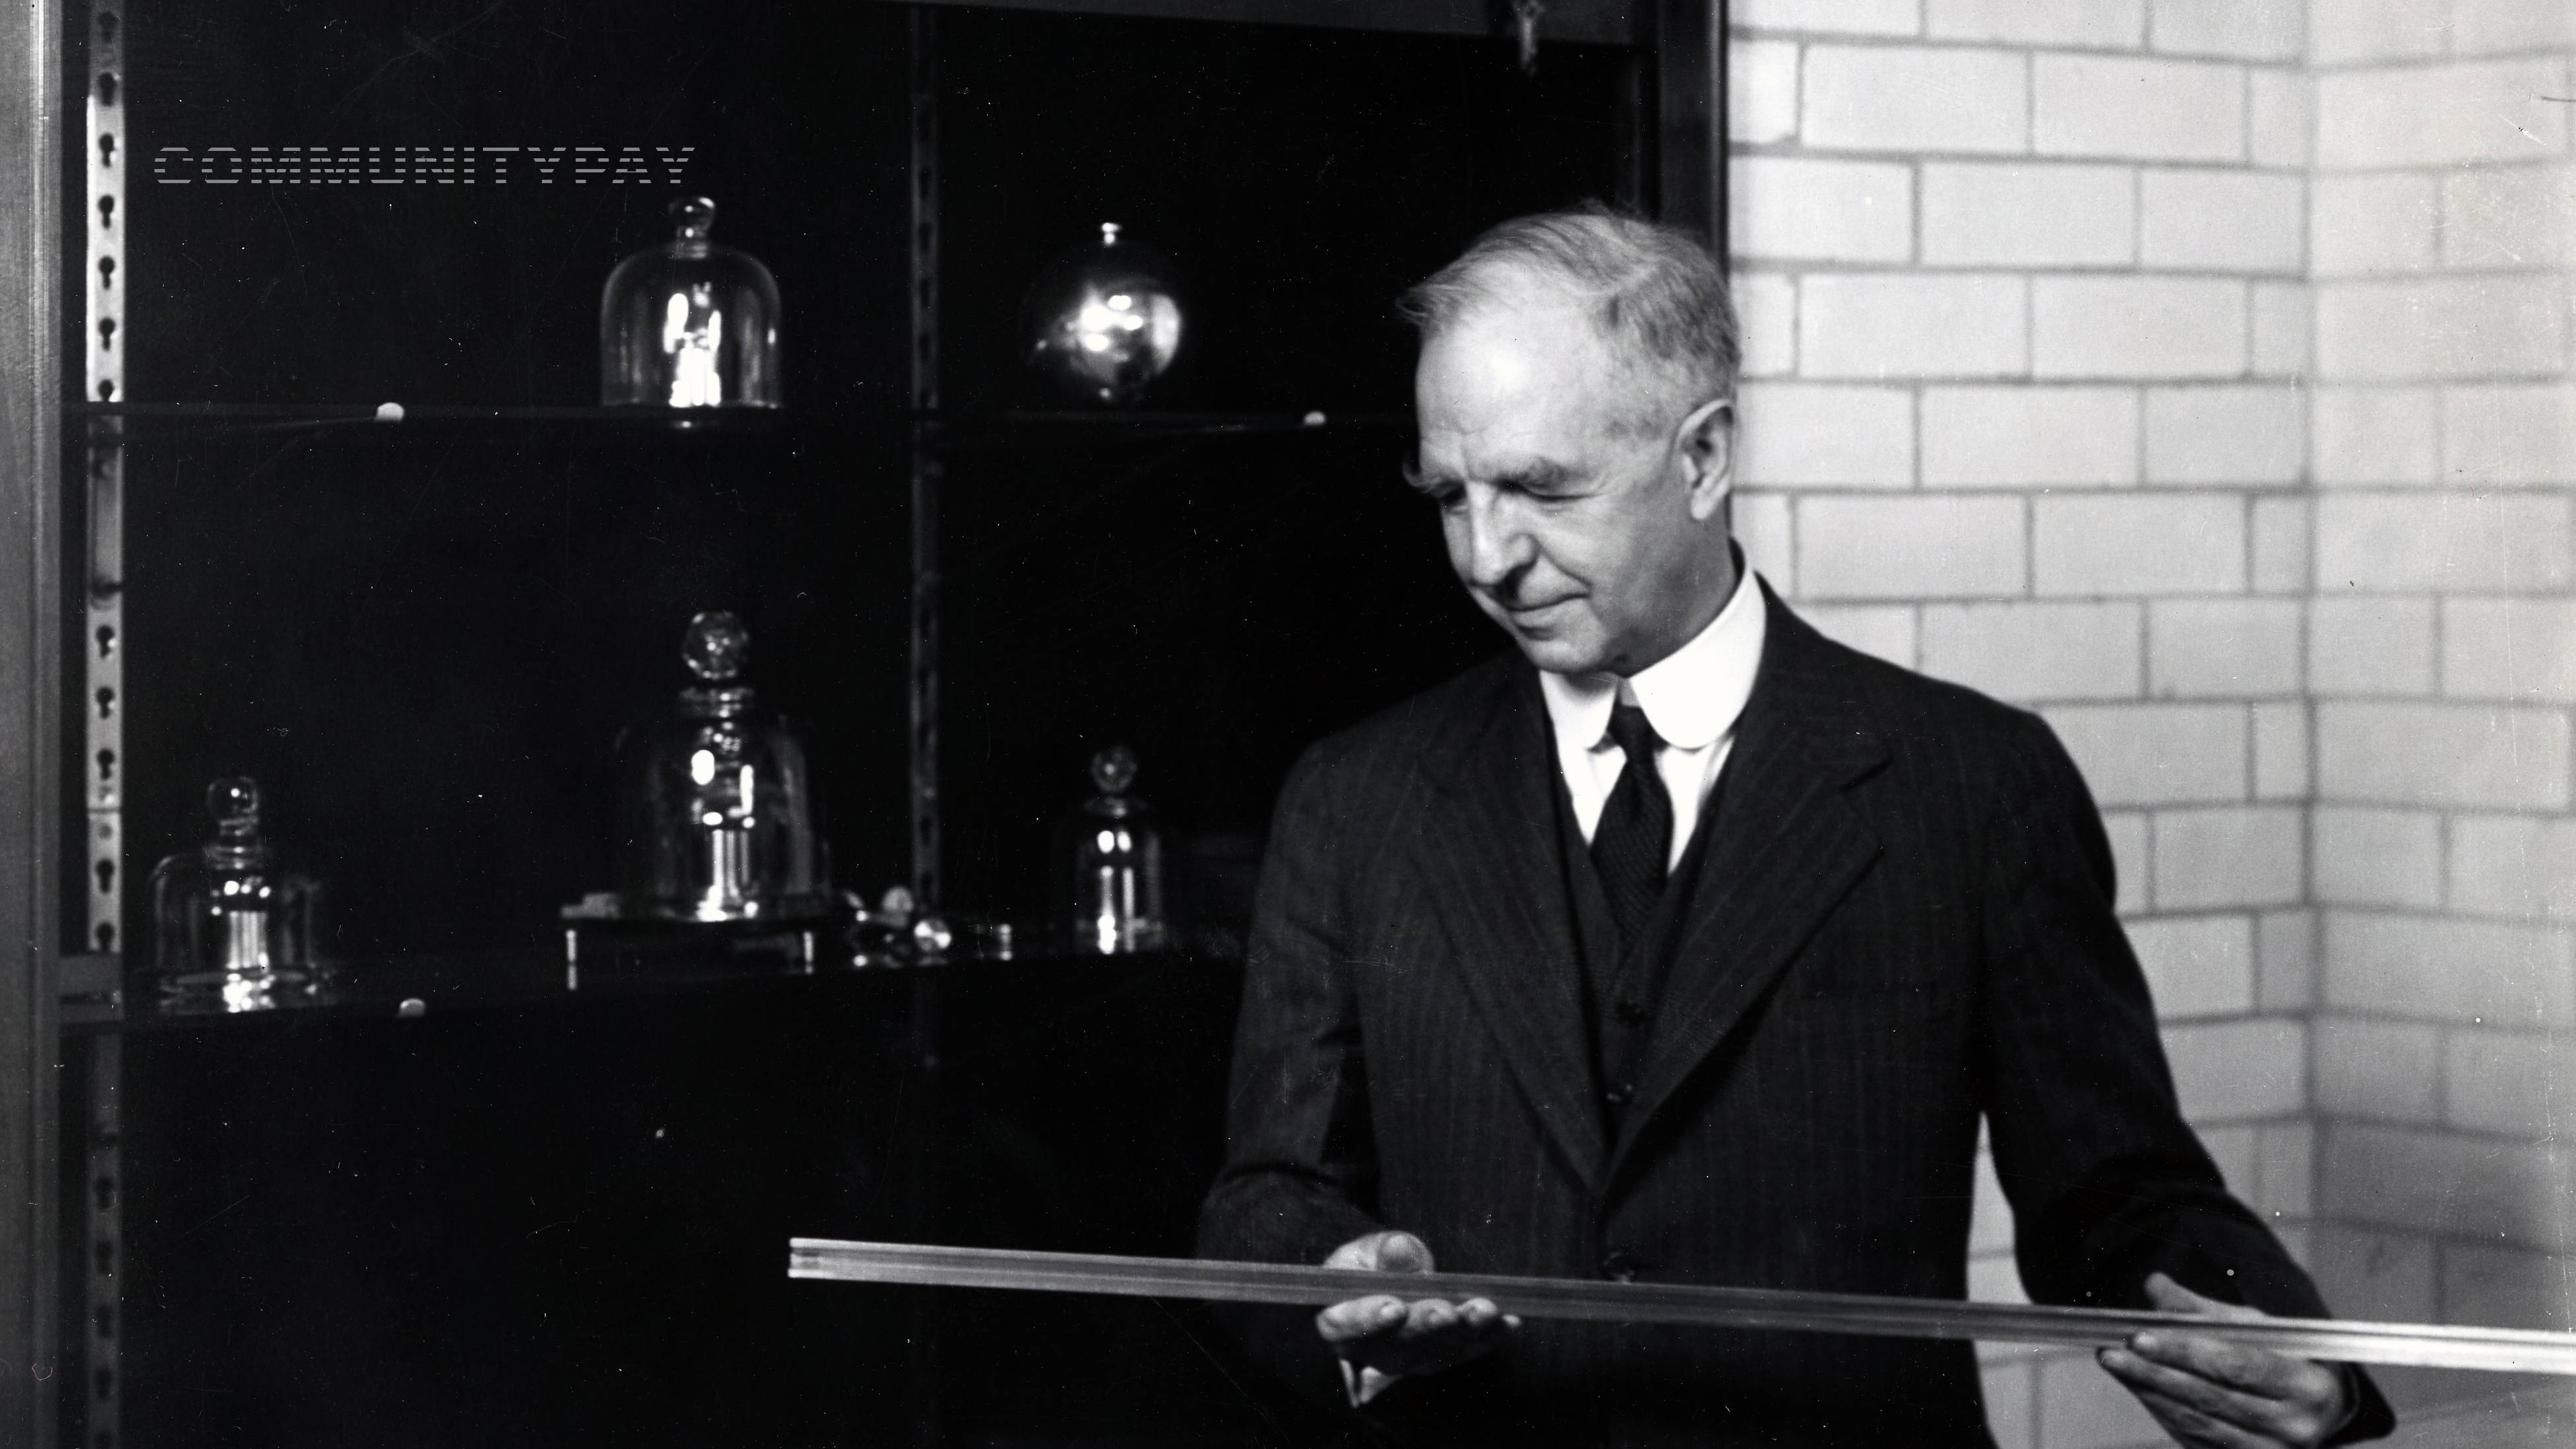
For 130 years the kilogram was an object. A cylinder of platinum and iridium sat under three bell jars in a vault at Sèvres, outside Paris, and every scale on earth traced to it — the balance in a pharmacy, the weighbridge at a port, the copy each nation kept in a vault of its own. The United States received its copy in 1890. The object had no customer. The bureau that kept it sold nothing.
Every market that handles other people's money has a measure like it. Banks have carried one composite rating from their examiners since 1979. Borrowers have carried a score since 1989. Bonds have carried a grade since 1909. The measure is not the regulation. It is the thing the regulator, the lender, and the buyer all read, so that two institutions a thousand miles apart can look at the same number and mean the same thing by it.
Community associations have none. There are 373,000 of them in the United States. Seventy-eight million people live in one, the homes inside them are worth $13.1 trillion, and the associations collect $124 billion a year in assessments to keep the roofs, the elevators, the garages, and the pipes. A lender writing a mortgage on a unit, an insurer writing the building, and a family buying the home are each betting on the association's finances, and each has one way to learn them: ask.
Asking works like this. After the collapse at Surfside in 2021, the two government-sponsored mortgage buyers began requiring lenders to ask every condominium project they fund about deferred maintenance, special assessments, and reserves. The association's manager or board fills in the form. The lender gets the answers and a signature. The reserve study behind the answers has an age of its own: in the Foundation for Community Association Research's 2022 survey, 31 percent of associations update theirs every five years. The insurer asks the same questions on its own form. The buyer gets a resale certificate during escrow, after the price is set.
Why is there no measure? Not because the figures are hard. Percent funded, delinquency, operating result, and special assessments are four lines on the statements every association already produces. It is because of where the figures sit and who holds them. The books of 373,000 associations are kept in 373,000 places, in a dozen software systems and a great many spreadsheets, by managers, bookkeepers, and volunteer treasurers. No one holds enough of them to publish a measure, and most of those who hold some have a stake in what the number would say: the management company whose contract is up for renewal, the reserve-study firm whose own figure would be the one graded, the lender who wants the loan. A measure any one of them computed would be read as a sales document, and the rest of the market would be right to read it that way.
What the missing measure costs is known in aggregate and invisible in particular. Association Reserves has prepared more than 100,000 reserve studies since 1986. Across all of them, 74 percent of associations held less than 70 percent of the reserves their own study called for. The share was 62 percent in the early 1990s and 72 percent in 2010 through 2012; in the firm's two most recent years it was 82 percent. The firm notes that these are its clients, not a census, and an association that never commissions a study is not in the count. A roof is replaced on schedule or by special assessment, and the owner who pays the assessment is the one who bought without a number to read. The lender who financed the unit priced the loan on a form. The insurer priced the building on a call. The drift from 62 to 82 percent happened in the open, one unread balance sheet at a time.
A standard changes three things. A lender can compare two buildings the way it compares two borrowers. An insurer can price the association it is writing instead of the category it falls in. And a board gets a number it can move: fund the reserve, collect the arrears, and watch the figure follow, instead of learning its standing from a buyer's lender.
For the measure to be a standard rather than a product, it has to meet the test the kilogram met. Every input must be a figure on the association's own statements, so that a lender, an auditor, or a treasurer holding the balance sheet, the income statement, the budget, the aging report, and the reserve study can recompute it. The method must be the same whoever runs it and wherever the books are kept, on a ledger that reads them nightly or typed in from a PDF, so that the number means one thing. And the party that keeps the method must hold no position in what it measures: no loans, no insurance policies, no reserve studies.
That is what CARI, the Community Association Risk Index, is built to be. The CARI score reads four things from an association's statements. Reserves, at 40 percent of the score: the balance over what fully funded would be, taken from the component schedule — each roof and each boiler, its replacement cost, its useful life, its age — or from the latest reserve study, or, where neither exists, from the contribution rate and the balance's cover of a year's expenses, marked as an estimate. Delinquency, at 25: units more than 60 days behind as a share of all units, and receivables more than 90 days old against a year's assessments. Operating, at 20: income over expenses for the trailing year, expenses against budget, and cash in months of expenses. Obligations, at 15: special assessments levied in two years and debt service, each against a year's assessments. The thresholds are not ours. The reserve bands are the 30 and 70 percent lines the reserve-study industry already uses; the delinquency ceiling is the 15 percent of units the mortgage buyers already allow; the contribution floor is their 10 percent of budget. When the statements do not carry enough of the figures, no score is issued. The method is published, with its curves, so that any vendor can compute it and any reader can check it.
The kilogram did not become the standard because the bureau at Sèvres sold it well. It became the standard because every scale could be checked against it and the bureau wanted nothing from the result. The association market has the figures, the institutions that need them, and seventy-eight million people living on top of the answer. It has lacked only the object in the vault. A standard is adopted, not sold.
Image: The standards vault at the National Bureau of Standards, November 16, 1939. Director Lyman J. Briggs holds Meter No. 27; Kilogram No. 20 sits under its bell jars on the second shelf. National Institute of Standards and Technology Digital Collections, Gaithersburg, MD 20899. Public domain.
Sources: International Prototype of the Kilogram, Bureau International des Poids et Mesures, 1889–2019. Uniform Financial Institutions Rating System, Federal Financial Institutions Examination Council, 1979. Foundation for Community Association Research, 2025 U.S. National and State Statistical Review, and Snap Survey, November 2022. Association Reserves, "74% of Association-Governed Communities Are Underfunded" and earlier portfolio analyses, 1986–2025. Fannie Mae Lender Letter LL-2021-14, October 2021.
Scott Vuilleumier · Founder of CommunityPay, Inc.
Data science, investment banking, and financial systems engineering and ledger design.